A spreadsheet, a debate among colleagues, and 1,000 AI-simulated investors walked into a retirement planning meeting…
Recently, our Retirement Solutions team found ourselves discussing a surprisingly simple question: Do risk tolerance questionnaires actually identify an investor’s true risk profile, or do they subtly nudge everyone toward the middle?
Rather than establishing focus groups and waiting months for participant data, I took a different approach. I leveraged AI to generate 1,000 synthetic responses to our existing risk tolerance questionnaire and compared the results to a completely different methodology: assigning investment recommendations based solely on age.
The exercise wasn’t intended to validate or invalidate our questionnaire. It was simply an experiment designed to test a hypothesis that emerged during team discussions. What we found raised more questions than answers. And honestly, those questions may be more interesting than the results themselves.
The Hypothesis
The original theory came from an observation made during one of our team discussions: Perhaps risk tolerance questionnaires naturally push people toward moderate recommendations. The logic seems reasonable. Most questionnaires ask questions like:
- How would you react if your portfolio declined?
- How much downside are you willing to accept?
- What level of volatility makes you uncomfortable?
- What would you do during a market selloff?
These are fundamentally emotional questions. They’re designed to measure comfort, not necessarily economic reality. If people generally dislike uncertainty, perhaps questionnaires naturally pull participants away from the extremes and toward the center.
The Experiment
For this analysis, I compared two recommendation approaches.
Method 1: Age-Based Investing
The age-only model was straightforward:
| Age | Recommendation |
| Under 35 | Aggressive Growth |
| 35-44 | Growth |
| 45-54 | Moderate |
| 55-64 | Moderate Conservative |
| 65+ | Conservative |
Under this simplified model, younger investors are assigned more aggressive recommendations, while older investors are assigned more conservative recommendations.
Method 2: Questionnaire-Based Investing
The second approach used our existing risk tolerance framework. The questionnaire evaluates:
- Investment objectives
- Time horizon
- Risk tolerance
- Retirement readiness
- Willingness to accept volatility
- Responses to market declines
The Results
Out of 1,000 AI-simulated investors, the differences between an age-only method and a questionnaire-based method jumped off the page:
Aggressive Growth recommendations dropped from 246 to 39, Conservative recommendations fell from 128 to 12. Meanwhile, Growth and Moderate categories swelled dramatically.
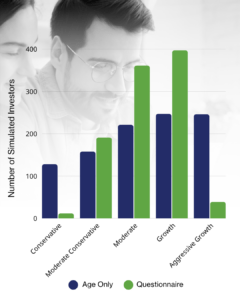
In other words, the questionnaire produced far fewer extreme recommendations and substantially more middle-ground outcomes. At first glance, the simulated results appear consistent with the hypothesis: The questionnaire generated substantially more middle-ground outcomes than the age-only model. But does it really?
Maybe We’re Comparing the Wrong Things
Here’s where I started questioning my own analysis. The entire experiment assumes that age-based investing is the benchmark. But why?
Age measures something very specific: Risk capacity. Risk capacity asks: How much risk can you afford to take? A 30-year-old investor who won’t need retirement assets for another three decades can generally withstand market volatility better than a 68-year-old retiree drawing income from the same account. Age is a reasonable proxy for capacity.
A risk tolerance questionnaire, however, is trying to measure something entirely different: Risk tolerance. Risk Tolerance asks: How much risk are you emotionally willing to take? Those are not the same thing. A 28-year-old who sells every time the market drops 10% may have tremendous risk capacity but very little risk tolerance. Likewise, a 70-year-old former entrepreneur who has experienced multiple bear markets may have substantial tolerance for risk despite having a shorter investment horizon.
So, if the questionnaire produces a different answer than age alone, is that evidence that it’s flawed? Or is it simply measuring something different?
The Risk Capacity Problem
The more I thought about the results, the more I found myself wondering whether many risk tolerance questionnaires may overweight emotional considerations relative to economic ones.
Consider a young investor. Traditional financial theory suggests younger investors should often hold higher equity allocations because they have more time to recover from market downturns. But if that same investor tells a questionnaire that they would panic during losses, dislike volatility, and worry constantly about market declines, they’ll likely receive a more moderate recommendation. That recommendation may be psychologically comfortable. But is it optimal?
Would Giving Risk Capacity Greater Weight Lead to Better Outcomes?
Possibly, but capacity cannot be considered in isolation. A recommendation that incorporates both risk capacity and risk tolerance may provide a more complete picture than one based solely on either factor. After all, retirement success depends on more than emotions. It also depends on:
- Time horizon
- Withdrawal needs
- Savings rates
- Retirement readiness
- Ability to withstand short-term losses
Ignoring those factors seems unwise.
At the same time, I’ve spent enough years around retirement plans to know that theoretically optimal portfolios don’t matter if participants abandon them at the first sign of trouble. After all, a strategy only works if the investor can stay committed to it when markets become uncomfortable.
My Takeaway
When we began this exercise, I thought we were evaluating a questionnaire. By the end, I realized we were examining a much bigger question: What matters more when making investment decisions, the risk investors can take or the risk they are willing to take?
The answer is likely neither on its own. The synthetic results show that the questionnaire generated substantially more moderate recommendations than the age-based model. That does not necessarily indicate a design flaw. It may simply demonstrate that the two approaches measure different dimensions of risk.
Perhaps the real opportunity is not to choose between risk tolerance and risk capacity, but to better understand how the two can work together.
The simulated investors were created solely for this exploratory exercise and should not be viewed as representative of an actual participant population. The results reflect the assumptions used to generate the synthetic responses and have not been validated using participant data. The analysis was intended to prompt discussion, not to draw conclusions about how real investors would respond.
The information provided in this blog post is for informational purposes only and should not be considered as financial, legal, or professional advice. Always consult with a qualified professional for specific advice tailored to your individual circumstances.